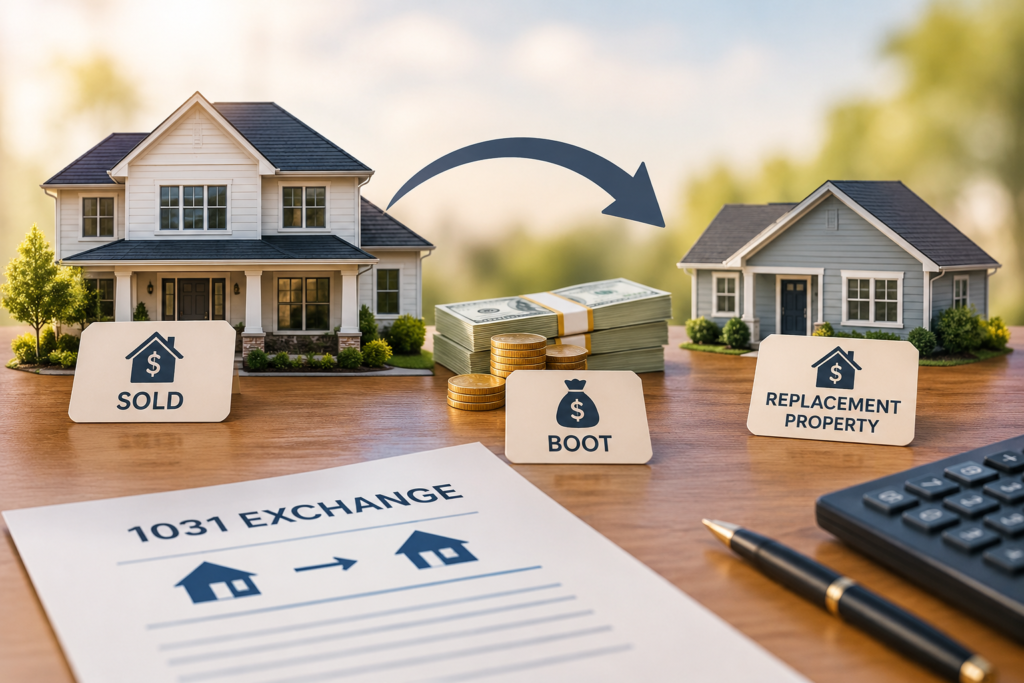
Yes, you can exchange a property for one of lesser value in a 1031 exchange—but doing so usually creates taxable income called “boot.” A 1031 exchange can still work as a partial tax deferral, but you generally will not defer all of your capital gains tax unless you buy a replacement property of equal or greater value and reinvest all of your net proceeds.
In simple terms: a 1031 exchange lets real estate investors sell an investment property and buy another qualifying investment property while delaying certain taxes. But if you “trade down” in value, the difference may be taxed now rather than deferred.
What Happens If You Buy a Cheaper Property?
Imagine you sell a rental property for $600,000. After closing costs, you have $580,000 in net proceeds. If you buy a replacement property for $520,000, you have $60,000 left over.
That $60,000 is commonly considered cash boot. It does not automatically cancel your 1031 exchange, but it can trigger taxable gain up to the amount of the boot received.
So, you may still defer tax on the portion reinvested into the new property, while paying tax on the cash or value you did not reinvest. This is why a lower-value replacement property is often called a partial 1031 exchange.
Why Equal or Greater Value Matters
To fully defer taxes in a 1031 exchange, investors generally need to meet two main goals:
- Buy replacement property with a value equal to or greater than the property sold.
- Reinvest all net proceeds from the sale into the replacement property.
If your new property costs less, the difference in value can become boot. Boot may include cash you receive, debt reduction, or other non-like-kind property received in the exchange.
For example, if you sell a property for $800,000 and purchase a replacement property for $700,000, the $100,000 difference may be taxable boot, assuming you have enough realized gain.
Debt Can Also Create Boot
Many investors focus only on the purchase price, but debt matters too.
If the property you sold had a mortgage of $300,000 and your replacement property has only a $200,000 mortgage, you have reduced your debt by $100,000. That reduction may be treated as mortgage boot, unless you offset it with additional cash invested in the replacement property.
To avoid debt boot, you generally need to do one of the following:
- Replace the old debt with equal or greater new debt.
- Add enough cash to the purchase to make up for the debt reduction.
- Use a combination of new debt and additional cash.
This is important because even if your replacement property costs the same as the old one, taking on less debt can still create tax exposure.
Can You Still Do a 1031 Exchange When Trading Down?
Yes. Trading down does not disqualify the exchange by itself.
You can sell a qualifying investment property, identify a replacement property within the required deadline, and complete the exchange. The key issue is that any value you do not reinvest may be taxable.
For example:
- You sell a property and receive $400,000 in net proceeds.
- You buy a replacement property for $350,000.
- You receive or retain $50,000.
- The $50,000 may be taxable boot.
You may still defer taxes connected to the $350,000 reinvested, but the $50,000 difference may be taxable now.
How to Reduce or Avoid Boot
If your goal is to defer as much tax as possible, plan the numbers before you sell. Here are practical ways to reduce boot:
- Buy a replacement property at an equal or higher price.
- Reinvest every dollar of net sale proceeds.
- Replace any debt that was paid off or reduced.
- Use exchange funds for eligible closing costs on the replacement property.
- Avoid receiving cash directly during the exchange process.
It also helps to work with a qualified intermediary and a tax professional before closing. Once you receive sale proceeds directly, you may lose the ability to use those funds in a 1031 exchange.
Is Trading Down Ever a Good Idea?
Sometimes, yes.
An investor may want a smaller property, less management responsibility, lower debt, or more accessible cash. A partial exchange can still be useful if the investor understands the tax cost of taking value out.
But if your main goal is maximum tax deferral, buying a property of lesser value is usually not the best approach. The safer strategy is to reinvest the full exchange value and replace the debt.
Exchanging a Property
You can exchange a property for one of lesser value in a 1031 exchange, but you may owe taxes on the difference. The lower-value purchase, leftover cash, or reduced mortgage debt can create boot, which may be taxable in the year you receive it.
If you want to defer the maximum amount of tax, aim to purchase a replacement property of equal or greater value, reinvest all net proceeds, and replace any debt reduction with new financing or additional cash.